All Categories
Featured
Financial Stability Planning Using Term Life Insurance
Ways to Get Competitive Individual Health Insurance Quotes

Final Expense and Burial Insurance for Seniors
Table of Contents
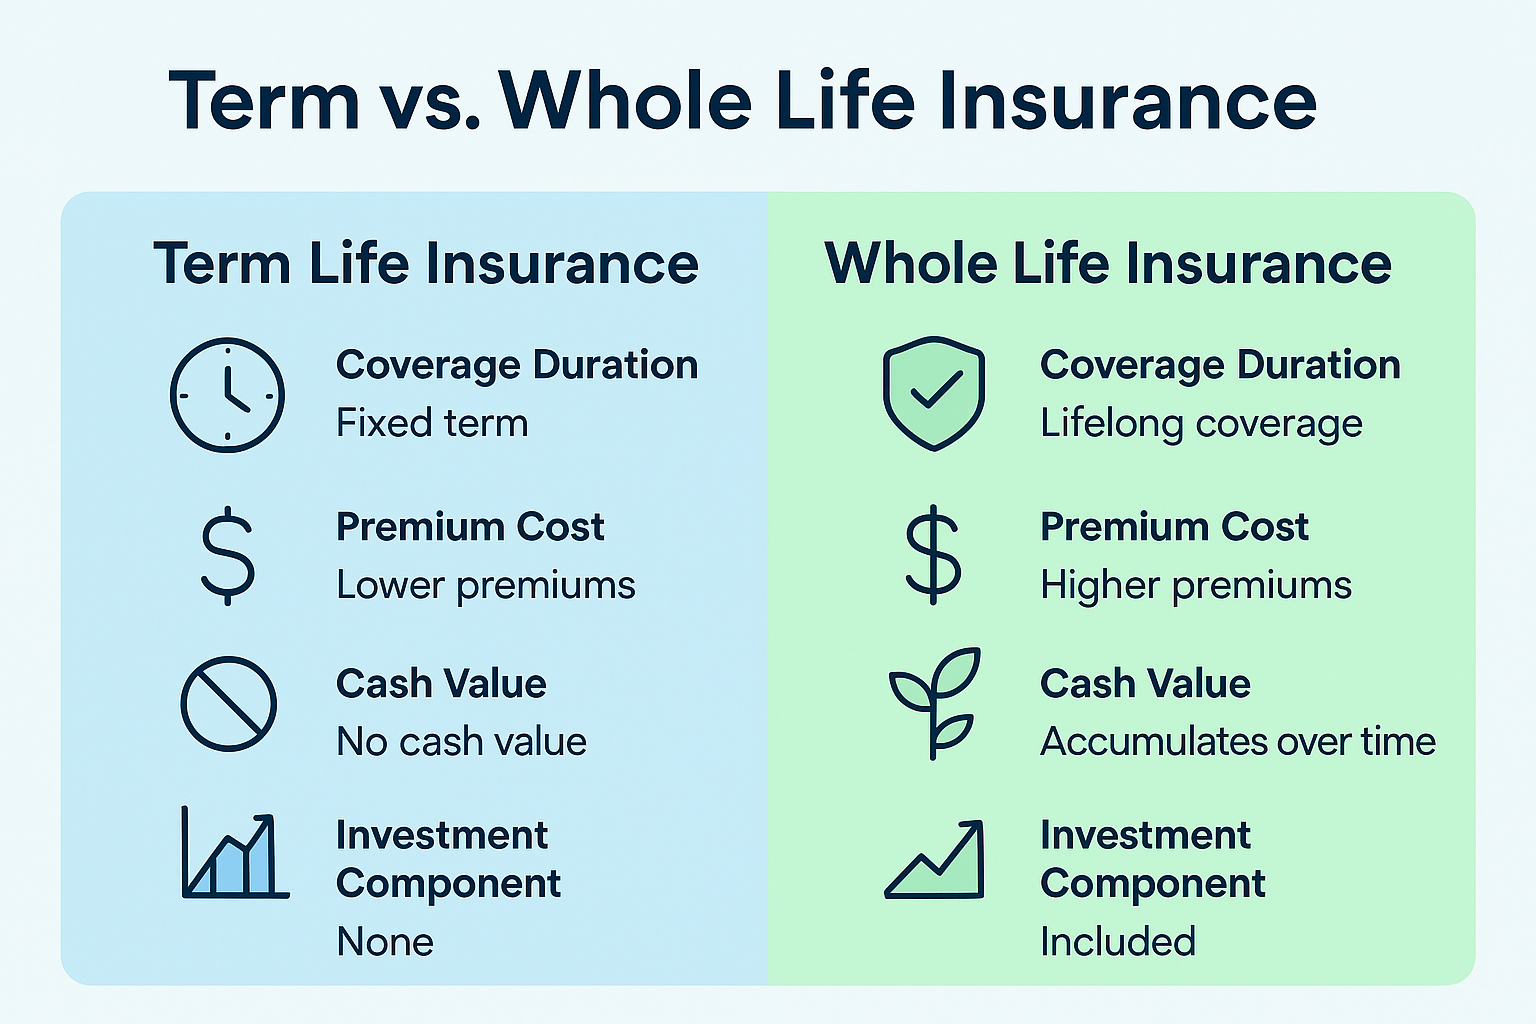
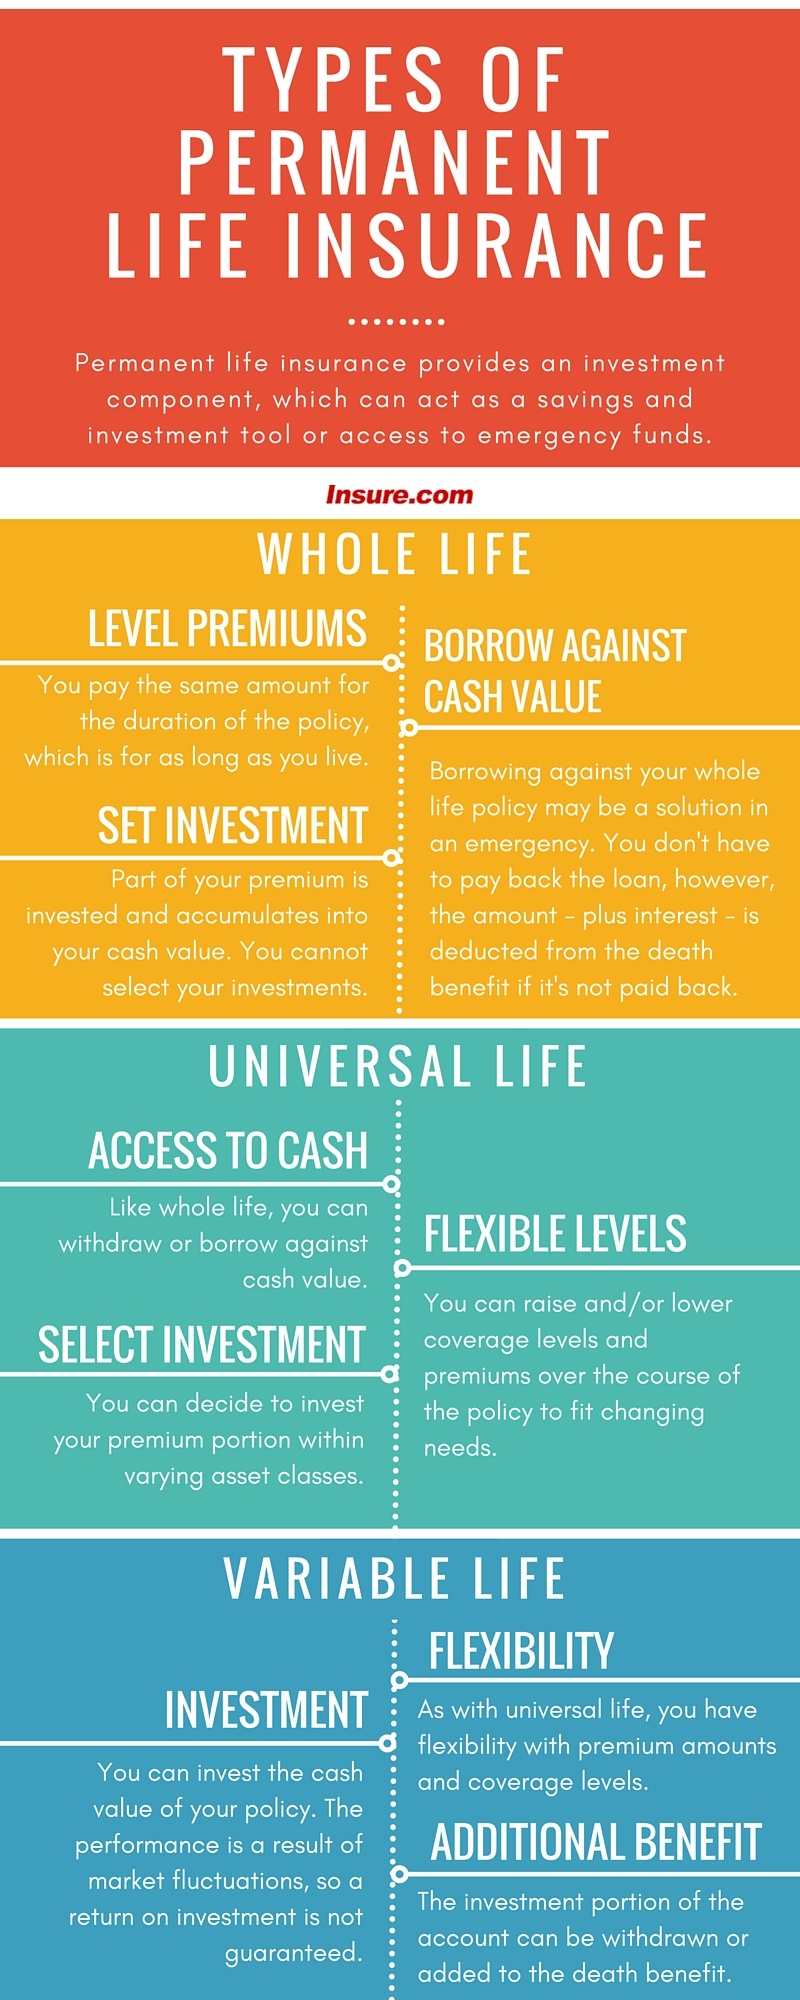
As quickly as the first premium is paid, the whole survivor benefit is set aside for your household. Income tax-free death advantage: The survivor benefit of a life insurance coverage policy is not generally based on federal income taxes. Tax-deferred development: The growth of cash worth inside of entire life insurance is tax-deferred while the funds stay in the policy.
This means withdrawals to the level of expense basis are thought about an income tax-free return of expense basis. Tax-favorable access to cash worth loans for any reason: During the insured's life, cash worth loans taken against an entire life policy are ruled out to be a taxable event, despite the fact that the policy might have a large gain in excess of premiums paid.
Insurance in Ventura CASelf-funding: The policy can pay for itself in time by applying dividends to pay premiums, which contributes to the policy's savings part. Special needs security: A whole life policy can continue to be moneyed even if you are disabled. When you choose the Waiver of Premium rider9, if you suffer a certifying special needs, your policy will continue to provide survivor benefit protection, have cash worth growth, and pay dividends even while you aren't paying premiums.

10Distribution: If correctly performed, life insurance coverage helps prevent probate and can provide recipients with higher privacy than may be paid for by a will; a will becomes public as soon as probated, whereas death advantage circulations are normally private, contractually driven transactions. Once a policy loan has been taken, the yearly dividend can be utilized to help pay back the policy loan.
Features, provisions, and expenses vary from one insurance provider to the next, and each entire life agreement is unique to the insurance policy holder. Entire life insurance rates depend upon factors such as age, health, and protection amount, so it's essential to think about these when assessing policies. Normally speaking, there are two fundamental types of payment structures for entire life: Level premium entire life: This is the most typical kind of entire life insurance coverage.
Insurance in Ventura CAIndividual Health Insurance Plans for 2026
Minimal payment whole life: This kind of policy has a fixed level premium like a level premium whole life policy, but the premium is just payable for a set amount of time. The advantage is that they are ensured to be paid up at the end of the payment period, so no payment is required at later ages.
Their accessibility and expense depends upon the policy and the insurance provider. In addition to the Waiver of Premium rider pointed out above, some other options provided by Guardian consist of: Paid-Up Additions Rider: The PUA rider can help increase the accumulation of tax-deferred money values and survivor benefit. The greater the premium paid into the rider, the higher the defense managed by the policy.
It provides you a special opportunity for index-linked upside potential and the floor guarantees that your year-to-year drawback market direct exposure is restricted. Accidental Survivor Benefit: Provides an additional death advantage if death takes place by unintentional bodily injury. Accelerated Benefit Rider: Supplies accelerated advantages, enabling you to access a portion of the survivor benefit early if you are detected with a chronic or terminal illness.
Medicare Part D Coverage and Prescription Drug Advice
Surefire Insurability Alternative (GIO): Gives the policy owner the right to acquire extra insurance without proof of insurability. The GIO can become much more valuable in case of disability: An insured who is disabled and has their premium waived may work out the GIO rider, and Guardian will pay the premium on the brand-new policy An entire life insurance policy is among the most essential monetary purchases you can make.
12 Comparing life insurance coverage business and their life insurance coverage offerings such as entire life, universal life, repaired premiums, ensured death benefits, and cash worth development is important to finding the ideal policy for your requirements. There are trusted, independent sources for monetary strength scores, such as A.M. Best, Moody's, Standard & Poor's and Fitch.
Discuss your situation with an insurance coverage expert or monetary specialist who understands whole life insurance and can assist you to the option that best meets your needs. If you do not know such an expert, ask a pal or colleague for a recommendation.
An entire life policy has cash value that grows in time. You can cash it out to assist supplement retirement, or obtain versus it at any time, for any reason. Whole life policies have a component referred to as the policy's money value: A part of your premium dollars can grow gradually on a tax-deferred basis, so you don't pay taxes on the gains.

Latest Posts

Financial Stability Planning Using Term Life Insurance
Individual Medical Insurance Quotes for 2026
The Mechanics of Whole Life Coverage