All Categories
Featured
Comparing Term and Whole Life Insurance Basics
Table of Contents
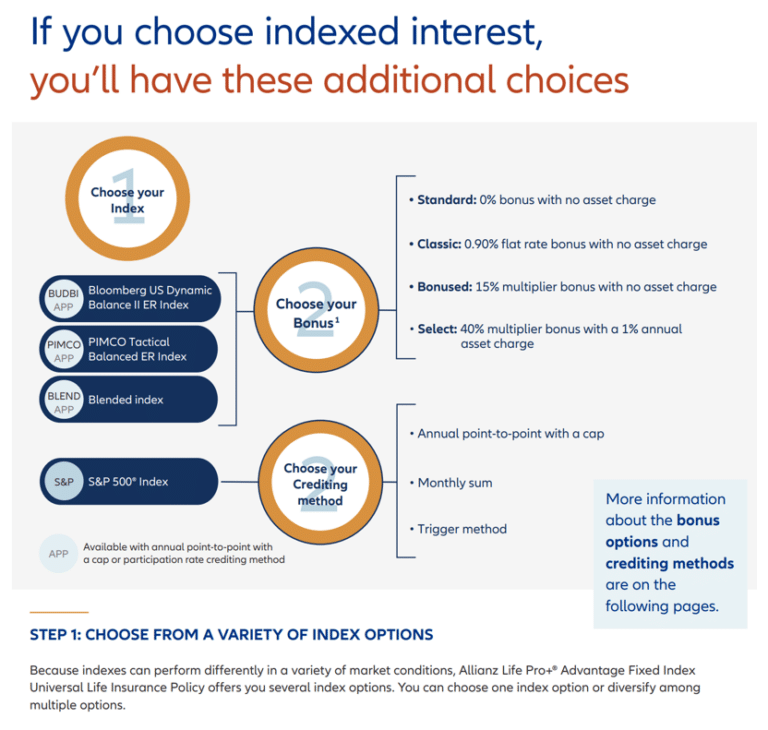
Nationwide likewise offers you the capability to essentially purchase additional upside potential with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage financial investment methods, which come with an extra 1%-2% cost. Although this lowers an IUL's flooring listed below 0%, there might be years when you want the extra advantage potential. Varied Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-lasting development, but lackluster early cash valuesParticipating policy loan rate is topped to be no higher than 8% Columbus Life Insurance Coverage is the IUL arm of the well-rated insurance coverage corporation of Western Southern Group, which entered the IUL arms race in the middle of the last decade.
Since their only obligation as a business is to the long-term commitment of insurance policy holders, they are most likely to do right by their inforce block of company. This can be plainly seen in this screenshot we just recently sent out to one of our clients revealing how Columbus Life's IUL cap rates have progressively increased from 8.75% in December 2022 to 10% exactly one year later as rates ticked up.
The worst IUL companies constantly claim to have the very best Indexed Universal Life insurance policy with the greatest cap. However, they'll begin with an extremely high cap to catch market share, then rapidly pull the carpet out from under their clients once they shelve that item and begin a brand-new one.
That method, insurance policy holders obtaining for outdoors investment opportunities still had the possible to earn at least some favorable arbitrage. Strong S&P 500 cap rateParticipating loan rate is capped at 6% (but has been lower for a while)Their recorded history of dealing with in-force policyholders fairlyMutual Holding Company without any outside stockholdersTheir uncapped indexed account is currently unsightly and inactionable.
To clarify, all the very best IUL business in this short article use some sort of totally free persistent illness rider, however National Life Group's is arguably the most robust. I likewise wish to point out that I am particularly discussing their "Peak Life" product, which is their "bigger case" product offering a more structured cost structure.
Top Indexed Universal Life Strategies for Retirement
Technically the rider is "free", but we've discovered when stress-testing charges that the mortality costs are a bit greater than other of the best IUL business."That stated, National Life Group is in the running for the best Indexed Universal Life insurance business for customers looking for a balance of efficiency, income, and extensive defense.
Don't spend excessive time on these information as your numbers will certainly vary, however this reveals the kind of chronic disease rider payments they use. to find out which are currently the best IUL policies with robust Chronic Health problem Riders and strong IUL crediting methods for tax-free income if you don't become too sick or harmed to operate independently.
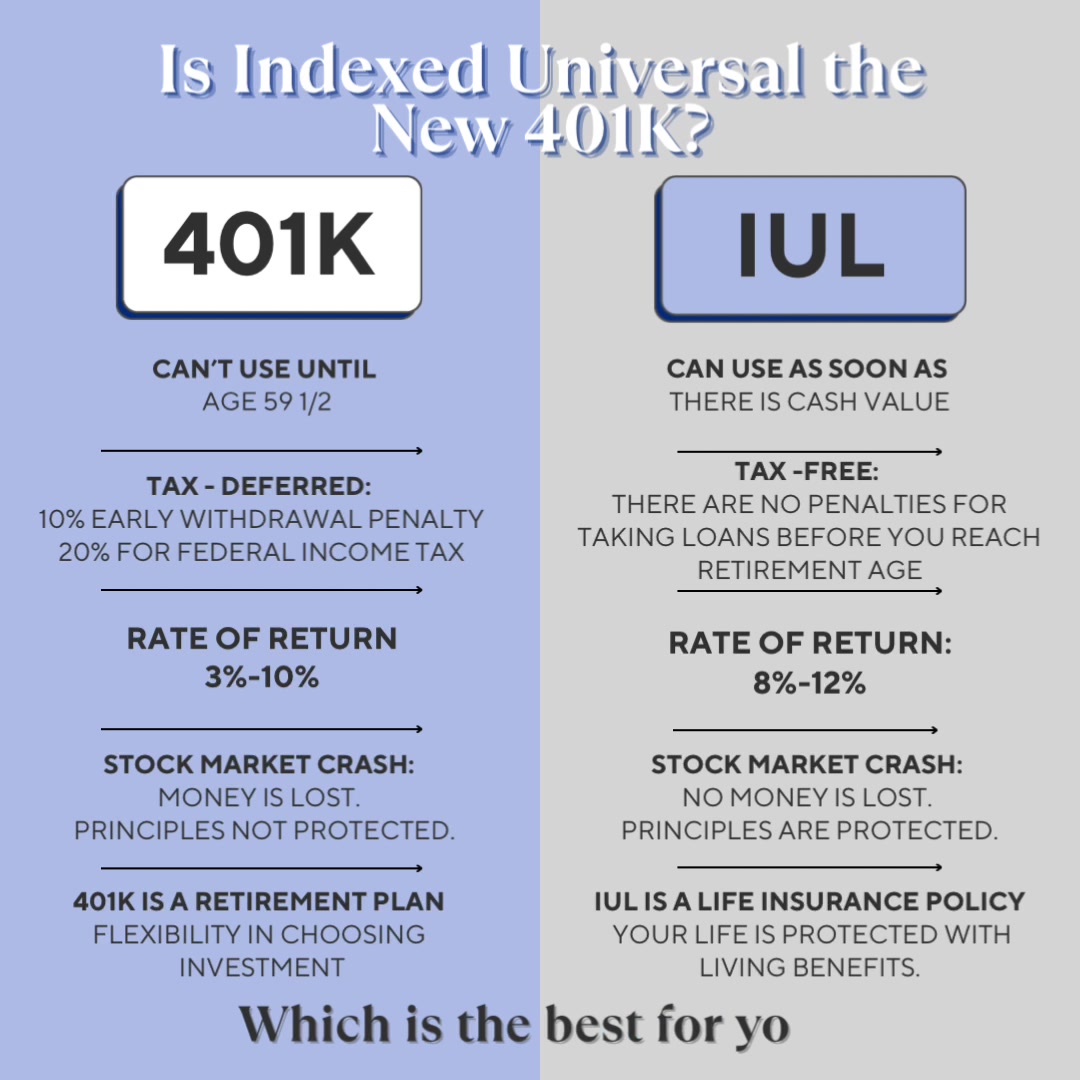
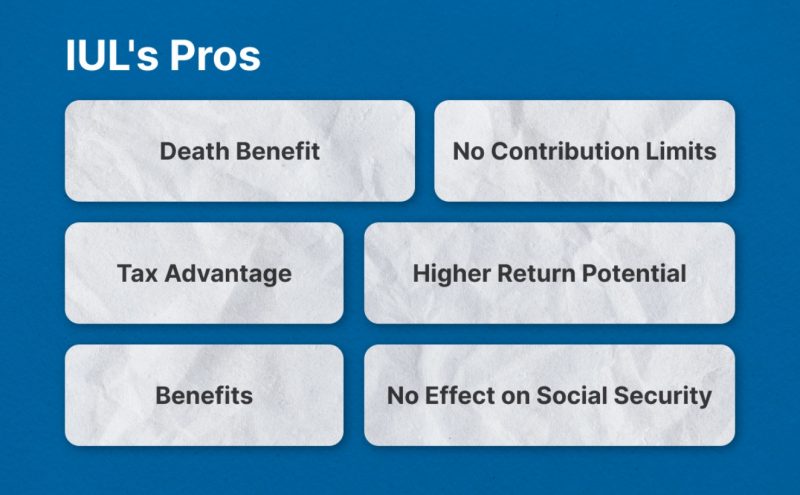
Indexed Universal Life Insurance coverage has many moving parts at its core, not to point out all the potential bells and whistles various companies add to their policies. Do not just succumb to an excellent story and slick sales pitch. now that you understand what to ask. If you're weighing IUL against your existing pension, our complete breakdown of covers the key differences in contribution limits, tax treatment, and flexibility.
Throughout the majority of the 1900s the only life insurance items were Whole Life and Term. Term insurance offered lower costs for momentary life insurance coverage. Whole Life offered a guaranteed survivor benefit for an ensured level premium, but also had a connected cost savings component with a guaranteed permanent development rate in addition to non-guaranteed dividends.
Insurance in Oxnard CAReviewing Family Health Quotes
The concept with Universal Life is that the growth of the savings account will lower the amount of pure insurance coverage in the policy, which would lower the increasing expense per system of death advantage. In 1986, soon after the meteoric increase of Universal Life, life insurance companies had the idea of including a financial investment element.
This caused the IRS restricting just how much premium anyone could pump into any quantity of irreversible survivor benefit for future tax-free retirement income. Regardless, as the stock exchange raved on throughout the 1990s, VUL became the insurance product of choice for money build-up. In 1997, the first Indexed Universal Life product was created by TransAmerica (not on the list of 2026 Finest IUL business). At first, Indexed Universal Life insurance coverage didn't make a huge splash at all.

Latest Posts
Evaluating PPO vs HMO Insurance

How Whole Life Insurance Functions
Securing Future Safety Strategies